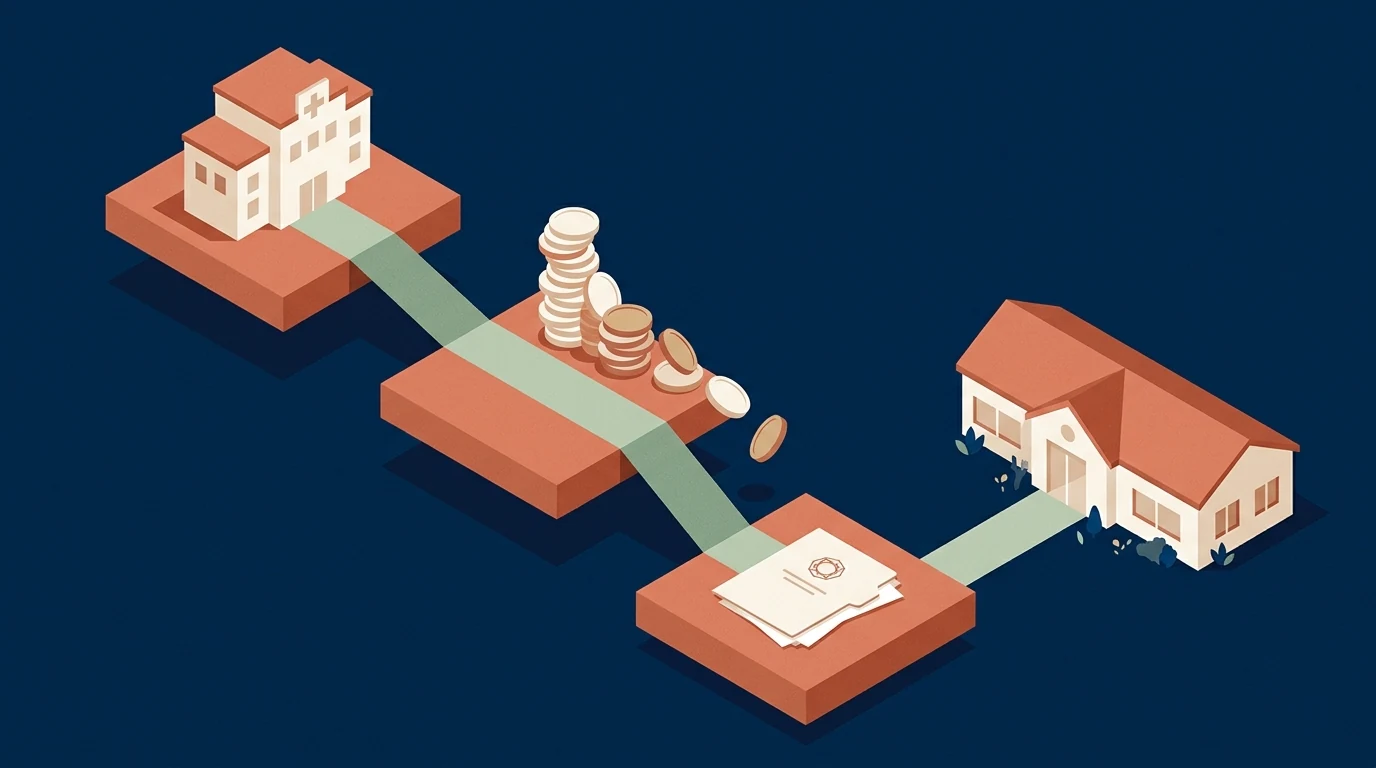
Most guides to paying for a nursing home give you a menu: savings, long-term care insurance, Medicare, Medicaid, VA benefits, pick what fits. If your parent went into a nursing home straight from a hospital, there is no menu. The payers take turns in a fixed order. Medicare pays first, for a short time and only for skilled care. Then your parent's own money pays, at full price. Then Medicaid pays, and from that point almost all of your parent's monthly income goes to the nursing home too.
You can't change the order. What you can change is the timing of each handoff, and that is where families win or lose tens of thousands of dollars. This post walks through the three stages, what ends each one, and the decisions you have to make before each handoff instead of after it.
Stage 1: Medicare pays for rehab, not for a long stay
Medicare is a short bridge, not a way to pay for a long stay. Part A covers a skilled nursing facility only after a hospital stay of at least three days as an admitted inpatient, and only while your parent needs daily skilled care such as therapy or wound care. Hospital time under "observation status" does not count toward the three days, even if your parent spent several nights in a hospital bed, per Medicare.gov.
The 100 days are a ceiling, not a promise. In 2026 the first 20 days cost nothing and days 21 to 100 cost $217 a day in coinsurance, according to the CMS 2026 fact sheet. Coverage stops as soon as the facility decides your parent no longer needs daily skilled care, which often happens well before day 100. Medicare never pays for custodial care, meaning help with bathing, dressing, eating and supervision. That is the care most long-stay residents actually need. We cover the day-100 cliff in detail in what happens when Medicare's nursing home benefit runs out.
The decision in Stage 1: use the Medicare weeks to prepare for Stage 3, not just Stage 2. While Medicare is paying, get copies of five years of bank and investment statements, find any life insurance policies and deeds, and find out whether this nursing home accepts Medicaid. Families who wait until private pay has started lose those weeks to paperwork while paying full price.
Stage 2: private pay, and how fast the money goes
The private-pay stage lasts as long as your parent's savings do, and in most states that is shorter than families expect. Our state data puts a semi-private room at $11,040 a month nationally in 2026 (based on Genworth's 2024 Cost of Care Survey, adjusted forward). CareScout's newer 2025 survey has the national median lower, at about $9,600 a month. Either way, the gap between the bill and a typical Social Security check is big. The average retirement benefit was $2,086 a month in July 2026, per the SSA monthly snapshot.
The table shows roughly how many months of private pay a given amount of savings buys. It assumes the state's semi-private median from our nursing home cost by state guide, and that $2,086 a month of income goes toward the bill. It leaves out other bills and any spouse at home.
| State | Semi-private / month | $50,000 lasts | $100,000 lasts | $200,000 lasts |
|---|---|---|---|---|
| Texas | $5,639 | 14 months | 28 months | 56 months |
| Ohio | $9,305 | 7 months | 14 months | 28 months |
| Florida | $10,652 | 6 months | 12 months | 23 months |
| U.S. median | $11,040 | 6 months | 11 months | 22 months |
| Pennsylvania | $12,187 | 5 months | 10 months | 20 months |
| New York | $15,164 | 4 months | 8 months | 15 months |
| Alaska | $31,282 | 2 months | 3 months | 7 months |
Other money can slow the drain, but it rarely changes the order. A long-term care insurance policy pays a daily or monthly benefit after an elimination period, most often 30 to 90 days, per the federal long-term care guide. Check whether the Medicare days count toward that waiting period, since policies differ. Veterans with a service-connected disability rating of 70% or more, or who need care because of a service-connected condition, can get nursing home care paid by the VA, per the VA. For most other families, Stage 2 ends the same way: the savings get down to the state's Medicaid asset limit.
The decisions in Stage 2:
- Don't give money away to "save" it. Gifts to children or anyone else in the 60 months before applying trigger a penalty period during which Medicaid won't pay, under 42 U.S.C. 1396p(c). A gift made now to stretch the money usually makes the gap longer. Our look-back period guide shows how each state calculates the penalty.
- Spend on things Medicaid allows. Paying off debts, prepaying a funeral, buying needed hearing aids or a wheelchair, and repairing the home are generally allowed. These purchases bring savings down without breaking look-back rules. See Medicaid spend-down by state.
- Don't sell the house just to pay the bill until you've checked the rules. The home is usually exempt while a spouse or dependent relative lives there, or while your parent intends to return. That protection is limited by a home equity cap that ranges from $752,000 to $1,130,000 in 2026 depending on the state. Once the house is sold, the cash counts as an asset and has to be spent down. The house question doesn't end there, though. The next section covers what happens after your parent dies.
Stage 3: Medicaid pays, and so does your parent's income
Medicaid doesn't take over the whole bill. It pays what your parent's income doesn't cover. Once your parent qualifies, nearly all of their monthly income, including Social Security and any pension, goes to the nursing home as their "patient pay" or "share of cost." Medicaid pays the rest at the state's rate. Your parent keeps a personal needs allowance, plus money for health insurance premiums such as the $202.90 Medicare Part B premium, and an allowance for a spouse at home if there is one. In our check of all 51 state Medicaid programs, the personal needs allowance runs from $30 a month in Alabama to $200 in Alaska. The full calculation is in how Social Security pays for a nursing home under Medicaid.
Getting into Stage 3 depends on two tests, and income trips up more families than assets do.
- Assets: usually $2,000 for a single person. There are exceptions. California's limit is $130,000 in 2026, New York's is $33,038, and Illinois's is $17,500. A spouse living at home can keep a protected amount, between $32,532 and $162,660 in 2026, depending on the state and the couple's assets.
- Income: in 24 states, income over $2,982 a month (300% of the federal SSI rate) disqualifies your parent no matter how little they own. The only fix is a Miller trust (a qualified income trust) set up before Medicaid will pay. Texas, Florida and Ohio are among these states. Most other states use a medically needy spend-down instead, where income over the limit goes toward the care bill each month. New York, Pennsylvania and North Carolina work this way. Check which kind your state is in our Miller trust guide before you file.
The house comes back into the picture after your parent dies. Federal law requires every state to seek repayment from the estates of Medicaid recipients 55 and older for nursing home costs, per Medicaid.gov. A house that was exempt during your parent's life is often the main thing in the estate. Recovery is deferred while a surviving spouse is alive, and states differ in how far they reach. See what states can take in estate recovery.
The handoff that costs the most: Stage 2 to Stage 3
Most of the avoidable losses happen at the move from private pay to Medicaid. The common mistake is waiting until the account hits the asset limit and then starting the application. A long-term care application often takes two to three months or more. If your parent can't pay in the meantime, the bill piles up.
Two rules make applying early the better move:
- Retroactive coverage is shrinking. Medicaid can currently pay bills from up to three months before the application month, if your parent was eligible then. For applications filed on or after January 1, 2027, that drops to two months for older and disabled applicants under the 2025 budget law. That makes a late application costlier from next year. See Medicaid retroactive coverage in 2027.
- A pending application protects the bed. A Medicaid-certified nursing home can't discharge a resident just because the payment source is changing to Medicaid, and nonpayment isn't a discharge ground while a Medicaid application is pending, under 42 CFR 483.15. That protection only works if the home accepts Medicaid and your parent is in a Medicaid-certified bed. Check this at admission, not at the handoff. Our post on which nursing homes accept Medicaid covers what to ask.
In practice, start the application when your parent's countable assets are within two or three months of the limit. Keep paying the home during that time, and keep every receipt from the spend-down. The paperwork stage is its own trap, covered in avoiding the paperwork denial.
A quick map of who pays when
| Stage | Who pays | What ends it | Decide before it ends |
|---|---|---|---|
| 1. Rehab after a hospital stay | Medicare Part A (days 21-100 at $217/day in 2026) | No more daily skilled need, or day 100 | Confirm inpatient status; gather 5 years of statements; check the home accepts Medicaid |
| 2. Private pay | Your parent's savings and income, LTC insurance, VA if eligible | Countable assets reach the state limit | No gifts; spend on allowed items; don't sell the house without checking the rules; file Medicaid 2-3 months before the limit |
| 3. Medicaid | Your parent's income first (minus allowances), Medicaid the rest | Death, discharge, or loss of eligibility | Miller trust in income-cap states; renewals; estate recovery planning for the house |
If your parent is going into assisted living instead of a nursing home, the order is different. Medicare doesn't pay for room and board at all, and Medicaid help comes through waivers with waitlists in many states.
Frequently asked questions
Who pays for nursing home care if my parent has no money?
Medicaid, if your parent meets the state's income and asset rules. Your parent's income still goes to the nursing home first, minus a small personal needs allowance and health insurance premiums. Adult children are generally not billed for a parent's care, though a few states have rarely used filial responsibility laws. See our post on filial responsibility laws.
Can the nursing home take my parent's house?
The nursing home can't, and Medicaid usually doesn't count the house while your parent is alive if a spouse lives there or your parent intends to return, up to the state's home equity limit. After your parent dies, the state's estate recovery program can claim against the house to recover what Medicaid paid, unless a surviving spouse or certain other relatives are protected.
How long will Medicare pay for a nursing home?
Up to 100 days per benefit period, and only while your parent needs daily skilled care after a qualifying three-day inpatient hospital stay. Days 21 to 100 cost $217 a day in 2026. Many stays end well before day 100 because the skilled need ends.
Should we apply for Medicaid before the money runs out?
Yes. Apply when countable assets are within a couple of months of your state's limit, not after they hit it. Approval takes time, retroactive coverage drops to two months for applications filed from January 2027, and a pending application protects your parent from discharge for nonpayment.
Nursing home payment rules vary by state, and this post explains the federal framework and common state practice. It is not legal advice. For Miller trusts, transfers, or a spouse at home, talk to an elder law attorney in your parent's state.
Sources
- Medicare.gov, skilled nursing facility care coverage
- CMS, 2026 Medicare Parts A & B premiums and deductibles
- 42 U.S.C. 1396p, transfers of assets, liens and estate recovery
- Medicaid.gov, spousal impoverishment (2026 CSRA and home equity limits)
- Medicaid.gov, estate recovery
- 42 CFR 483.15, admission, transfer and discharge rights
- 42 CFR 435.725, post-eligibility treatment of income
- Public Law 119-21, Section 71112 (retroactive coverage)
- ACL, receiving long-term care insurance benefits
- SSA, Monthly Statistical Snapshot
- State figures: Elder Care Index's 51-state Medicaid check (November 2026, against state agency sources) and state cost data (Genworth Cost of Care Survey 2024 adjusted to 2026, with CareScout).